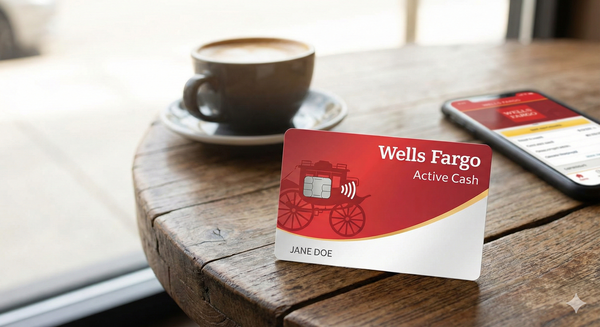
👍 The Good Stuff
- ✅ 2% Everywhere: No caps, no categories, no nonsense.
- ✅ $200 Bonus: Easy to earn (Spend $500 in 3 months).
- ✅ Cell Phone Protection: Up to $600 coverage if you pay your bill with the card.
- ✅ 0% Intro APR: 12 months on purchases and balance transfers.
👎 The Bad Stuff
- ❌ Foreign Fees: 3% fee makes it bad for international travel.
- ❌ Redemption Min: ATM redemptions require $20 increments.
- ❌ Boring: Zero "fun" perks like lounges or status upgrades.
The Deep Dive
The card for people who are tired of doing math at the checkout counter. It earns 2% cash back on everything, from diamond rings to breakfast burritos.
The Math (It Just Works)
The $200 bonus is what sets this apart. Most 2% cards (like the Citi Double Cash) don’t give you a bonus. Wells Fargo is paying you $200 just to try it out.
- Annual Fee: $0.
- Cash Back Rate: 2% Unlimited.
- Sign-up Bonus: $200 (after spending $500).
Active Cash vs. Citi Double Cash
This is the heavyweight title fight of the boring credit card world. Both earn 2% on everything with $0 annual fees. However, Wells Fargo wins on two fronts: It usually has a $200 Sign-Up Bonus (Citi rarely does), and it includes Cell Phone Protection (Citi stripped most insurance benefits).
The Cell Phone Protection (Hidden Gem)
This is rare for a no-fee card. If you pay your monthly cell phone bill with the Active Cash, you get up to $600 of protection against damage or theft. There is a $25 deductible, which is peanuts compared to the cost of a new iPhone screen.
Who Should Get This Card?
- You want one card for everything and hate tracking categories.
- You want a $200 bonus for very little spending ($500).
- You pay for cell phone insurance and want to stop paying for it.